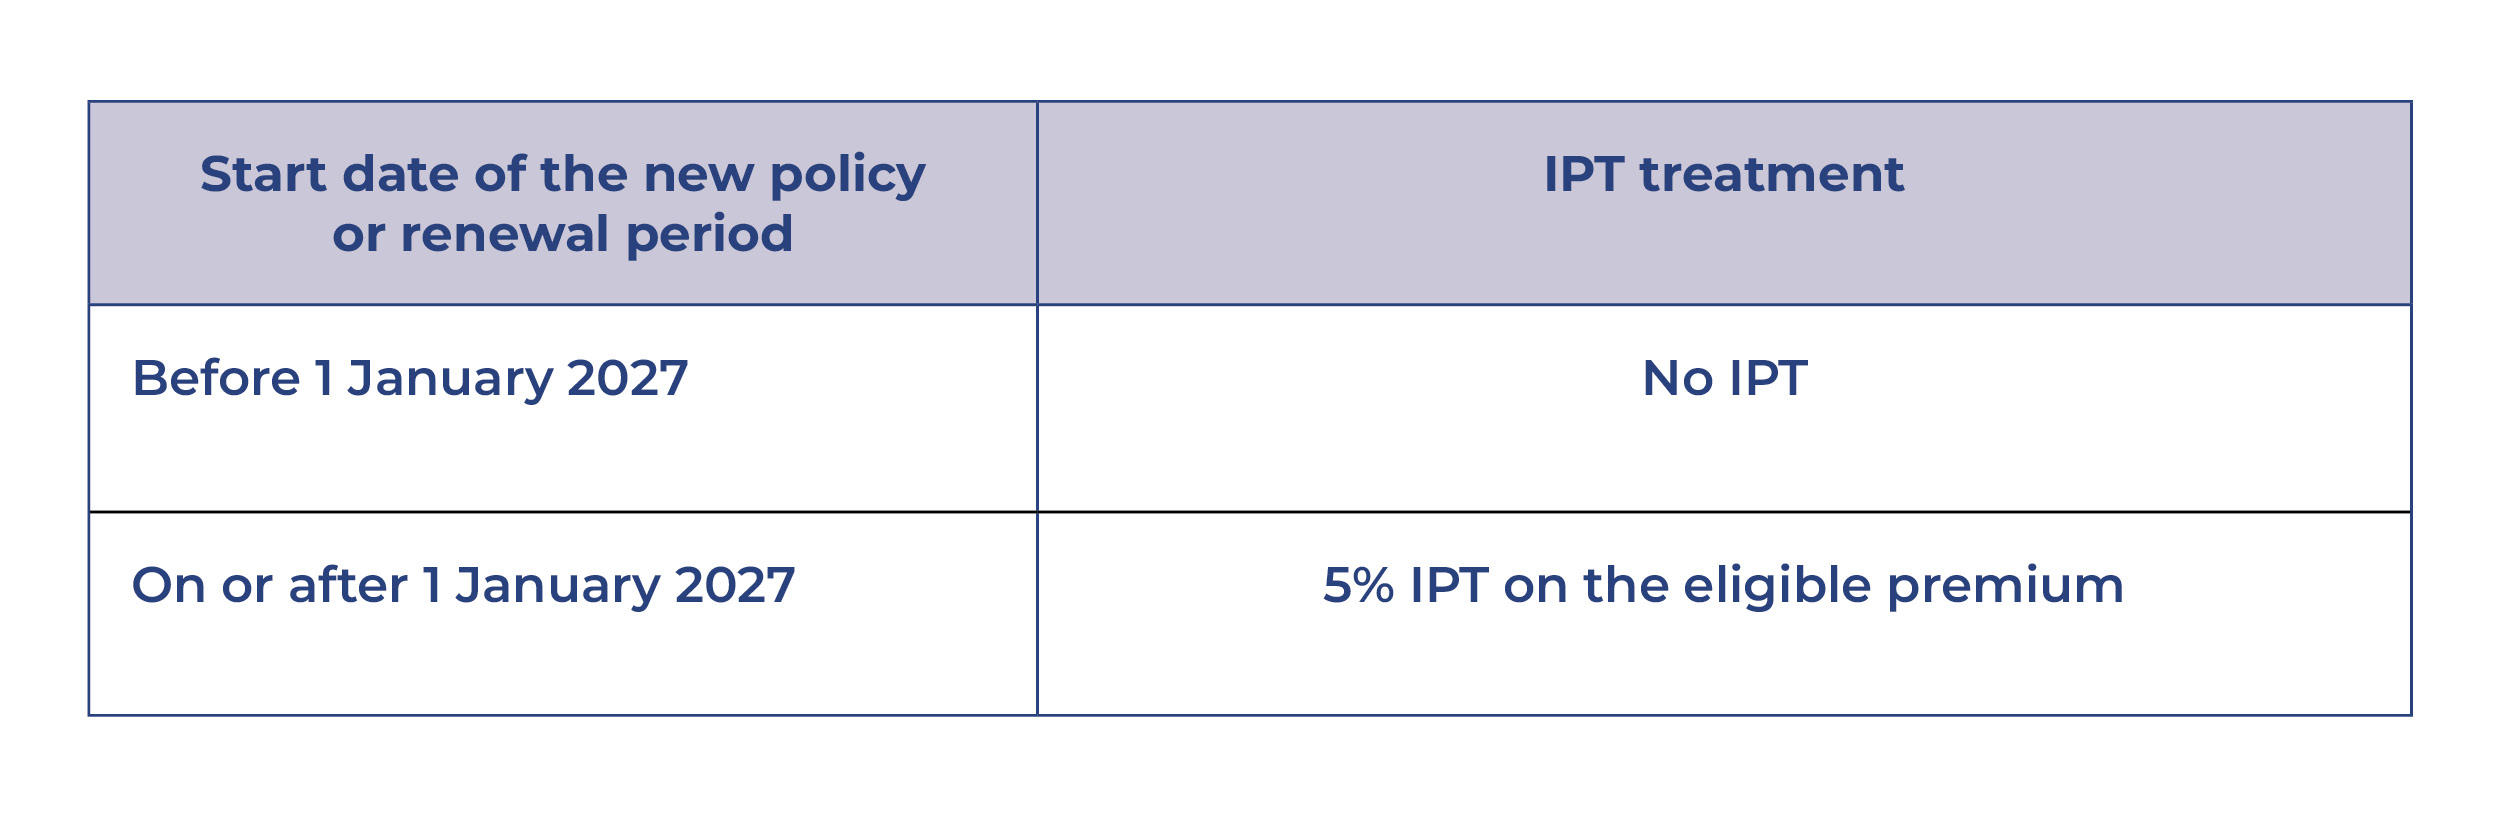
Under the Finance Act 2026, a 5% Insurance Premium Tax (IPT) will apply to insurance premiums for new policies and renewals with a start date on or after 1 January 2027.
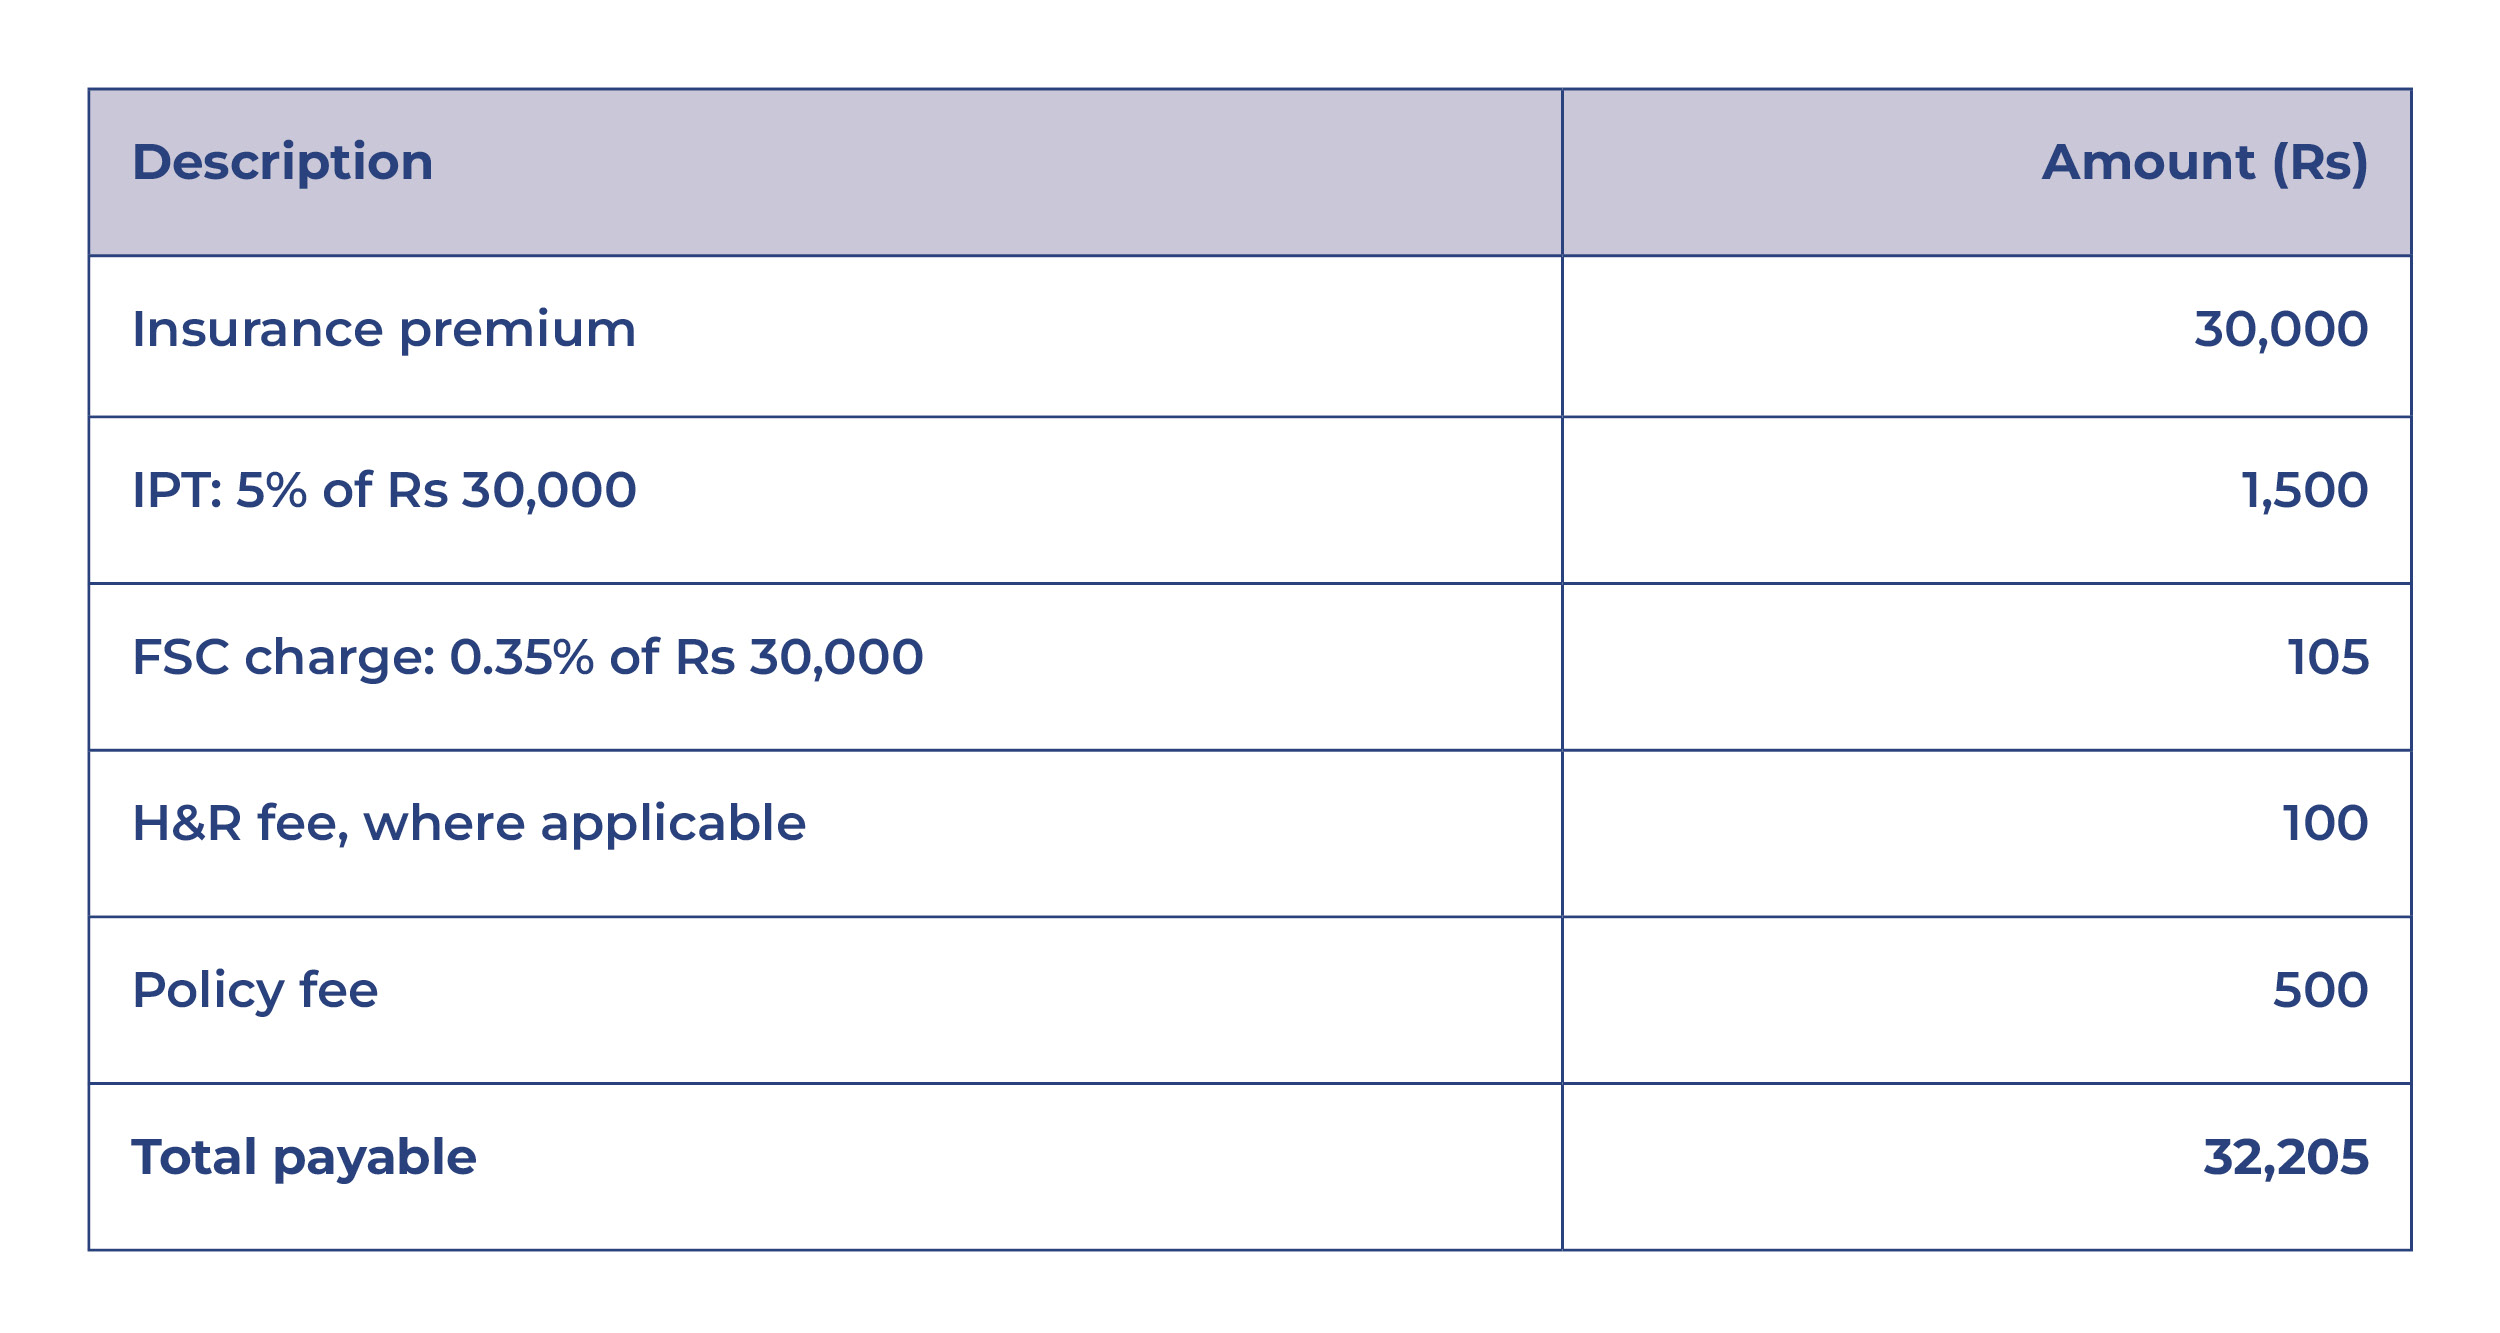
IPT will be collected on premiums paid to us and remitted to the Mauritius Revenue Authority (MRA) within the applicable statutory deadlines. IPT will be calculated on the insurance premium after applicable discounts and adjustments. FSC charges, policy and endorsement fees, and Hit and Run (H&R) fees, where applicable, are excluded from the IPT calculation.
Which policies will be subject to IPT?
The determining date is the start date of the new policy or renewal period, regardless of when the renewal notice or invoice is issued, or payment is received.
For example, a renewal starting on 1 January 2027 will attract IPT even if the renewal notice is issued or payment is received in December 2026. Conversely, a policy starting before 1 January 2027 will not attract IPT simply because it is invoiced or paid after that date.
How is IPT calculated?
The example below illustrates the calculation for a policy subject to IPT. The insurance premium shown is after applicable discounts and adjustments.
In this example, a 5% tax of Rs 1,500 has been added to the total amount payable. No IPT is charged on the FSC, H&R or policy fee.
For more information, email us at [email protected] or call 460 9200. If your policy is managed through a broker or an agent, you may also contact them for assistance.